Keeping or Selling the Marital Home in Huntersville: A Divorce Planning Worksheet
Adkins Law • Huntersville, North Carolina • Divorce & separation
A plan for the marital home must answer three separate questions: who owns it, who owes the lender, and who can afford the costs. A deed transfer or divorce agreement does not automatically release a borrower from the mortgage.
- Classify ownership
- Confirm loan liability
- Test the monthly budget
Look beyond the estimated equity
The family home can represent school stability, memories and a large part of the marital balance sheet. For Huntersville and Lake Norman homeowners, the first useful step is a complete property file: deed, mortgage statements, home-equity loans, purchase records, tax information, insurance and any appraisal.
North Carolina’s equitable-distribution statute distinguishes marital, separate and divisible property. Classification may be complicated by ownership before marriage, inheritance, refinancing, contributions and changes in value. Do not assume that the name on the deed alone answers the division question.
Compare the options on the same basis
| Option | Potential benefit | Question to resolve |
|---|---|---|
| Sell the home | Can create a clearer financial separation | Who selects the agent, sets the price, pays repairs and holds proceeds? |
| One spouse keeps it | May preserve a familiar home and routine | How are valuation, buyout funding and release from the loan addressed? |
| Temporary shared ownership | Can allow time for a planned transition | What is the exit date, and what happens if a payment or refinance fails? |
Each path needs specific terms. An agreement to “sell later” leaves open questions about access, repairs, showings, price reductions and what happens if one person does not cooperate. A promise to refinance needs a deadline and a workable fallback if the lender declines.
Separate title from debt
The Consumer Financial Protection Bureau explains that allocating a debt in divorce generally does not change the creditor’s rights against a borrower. Removing a name from title does not remove it from the loan.
Ask the servicer and your lawyer about the loan’s actual requirements, including whether an assumption, refinance or contractual release is available. Do not assume that every loan permits the same solution or that an ownership transfer guarantees release of liability. Keep written confirmation of the lender’s decision.
An illustrative equity calculation
Example only—not a valuation or proposed legal division:
Hypothetical agreed value: $500,000
Less hypothetical loan payoff: $300,000
Simple equity before other adjustments: $200,000
Sale costs, liens, repairs, taxes, separate-property claims and the overall settlement may change the analysis. This chart is arithmetic, not a prediction of what either spouse receives.
A proposed buyout should also be compared with the rest of the estate. Giving up retirement funds for home equity may affect liquidity, taxes and future security. The values on a spreadsheet are not necessarily equally spendable dollars.
Test a realistic monthly budget
List principal and interest, taxes, insurance, association dues, utilities and a maintenance reserve. Add child care, transportation, food, health coverage and other debts. Use a lender’s actual estimate if a new loan would be needed; the current mortgage payment may not survive a refinance.
Then ask what happens if expected support is delayed, income falls, or a major repair arrives. A plan that works only in the best month may create a second dispute. Your lawyer and appropriate financial or tax advisers can help assess the assumptions.
Preserve the property claim before divorce
Before an absolute divorce is entered, confirm that any equitable-distribution claim you need has been properly preserved. Review G.S. 50-11 with counsel rather than assuming negotiations alone protect the claim.
Read about property division at Adkins Law and bring this worksheet to a divorce consultation. Chris Adkins’s profile provides background on the firm’s family-law work.
Your preparation checklist
Check items as you prepare. This checklist does not submit information to the firm and is not saved when you reload the page.
Common questions
Select a question to expand the answer.
Does moving out automatically give up my ownership?
Do not assume that physical possession determines property rights. Ask counsel about your particular ownership, support, custody and safety circumstances before making a planned move.
Does a quitclaim deed remove my mortgage obligation?
A deed changes title. It does not by itself release a borrower from a loan; obtain advice and written lender confirmation.
Can we agree to sell after the school year?
A negotiated transition may be possible, but the agreement should address payments, use, maintenance, sale mechanics and a fallback if the plan fails.
Related planning guides
- Your First Divorce Consultation in Huntersville: A Practical Preparation Guide
- Digital Records During a North Carolina Separation: What to Save and How to Organize It
- A Better Child Custody Exchange Plan: Practical Questions for North Carolina Parents
Sources and publication notes
- G.S. 50-20: equitable distribution
- G.S. 50-11: preservation of property claims
- CFPB: debt responsibility after divorce
Information checked October 4, 2026. Prepared for Adkins Law with AI-assisted drafting and source checks. General legal information, not advice for a particular case. Laws, court procedures and individual circumstances can change the analysis. Illustrations and examples are hypothetical, not client results.
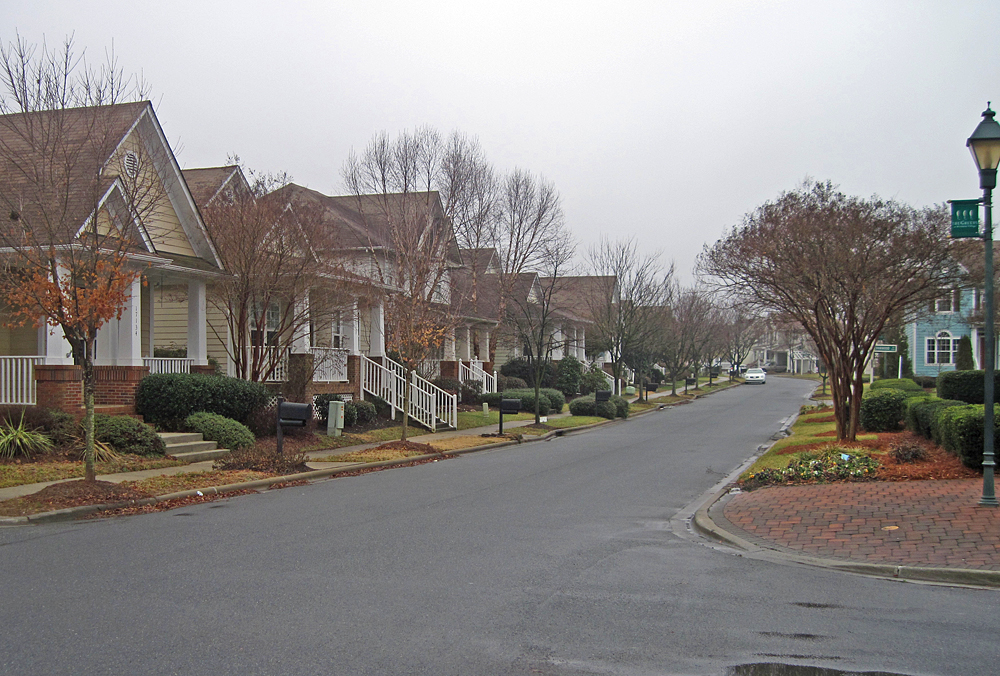
Featured photograph: Homes facing a park in Birkdale Village, Huntersville. Photographed September 15, 2009. Photo: Brett VA / Wikimedia Commons, CC BY 2.0. Archival community view; no connection to any case or endorsement is implied.

Share This Story, Choose Your Platform!
Disclaimer: This website provides general information and discussion about legal topics. The content is not legal advice and should not be relied upon as such. Always seek the advice of a licensed attorney for legal matters.